THURSDAY, OCTOBER 8, 2026  /  10-MINUTE READ

CASH & CHAOS

MARKETS, MONEY AND THE MADNESS IN BETWEEN.

In partnership with

Good morning. TSMC’s chip factories are still busy. PepsiCo is selling more, but keeping less of the benefit. And Washington has offered Wolfspeed a financing package that could change its balance sheet—provided the company clears a long list of conditions.

Futures are lower before the bell. Today’s earnings and financing announcements give us more to work with than another round of guesses about AI demand.

BEFORE THE BELL

−0.46% S&P 500
7,816.25
−0.66% Nasdaq 100
31,194.75
−0.83% Dow
51,021.00

December futures · October 8, 7:43 a.m. ET · delayed Yahoo Finance quotes; change versus prior close.

THE BIG STORY · TSM

TSMC’s sales jump 55%. The stock still slips.

TSMC Global Research and Development Center at night

TSMC R&D Center · 曾 成訓 / Wikimedia Commons · CC BY 2.0

TSMC reported NT$511.86 billion in September revenue, up 54.6% from a year earlier. That brings sales for the first nine months of 2026 to NT$3.90 trillion, up 41.1%. AI customers are still putting serious money through its factories.

The U.S.-listed shares were nevertheless down 1.55% at $464.88 at 7:52 a.m. ET, according to Yahoo Finance’s premarket feed. Strong reported growth and a falling share price can coexist, especially on a weaker morning for markets.

September was 0.6% below August. That small sequential decline sits alongside a much larger annual increase; treating it as evidence that the chip boom has suddenly stopped would be a stretch. Monthly deliveries can shift without changing the underlying direction of demand.

Adding the monthly figures puts third-quarter revenue at roughly NT$1.49 trillion, above the NT$1.46 trillion analyst estimate cited in the linked report. The precise dollar comparison depends on exchange rates, so the Taiwan-dollar figures give us the cleaner comparison here.

TSMC makes the chips designed by companies including Nvidia, AMD and Apple. That gives its sales report a useful role in the AI debate: it measures manufacturing revenue across customers, rather than the spending ambitions of a single buyer. It does not tell us which chip designer is winning every order.

More business through an expensive factory can spread fixed costs across a larger revenue base. But new plants, production ramps and the mix of chips being shipped also affect how much becomes profit. Today’s release supplies the sales number, not the full margin picture.

Full third-quarter results arrive October 15. Management’s margin figures and fourth-quarter outlook will tell us more about the economics behind this growth. For now, the company has delivered another large sales increase. Investors are still deciding how much of that was already in the price.

See the quarterly sales comparison →

EARNINGS · PEP

PepsiCo beats the quarter, then lowers the bar.

PepsiCo headquarters in Purchase, New York

PepsiCo headquarters · Peter Bond / Wikimedia Commons · CC BY-SA 2.0

PepsiCo cleared Wall Street’s quarterly estimates this morning. Core earnings were $2.34 a share versus $2.29 expected; revenue reached $25.27 billion versus $24.95 billion. The comparisons use FactSet estimates reported by MT Newswires.

The less comfortable number was the full-year outlook. PepsiCo now expects core EPS growth of 2.5%–3.5%, down from the low end of its previous 5%–7% range. A quarterly beat is welcome. A lower earnings forecast tells investors that the rest of the year will be harder than management had planned.

Sales rose 5.6%, but organic growth—which strips out currency and portfolio effects—was 3.1%. Core operating margin fell 35 basis points to 16.9%, while core EPS grew just 2%. More money came through the door without a matching increase in adjusted earnings.

The North American volume figures help explain why. Food volume was flat, and beverage volume declined 2%. Revenue can rise through pricing and a different product mix even when customers are buying fewer units. That leaves less room to spread operating costs across a growing number of products sold.

PepsiCo also said tariff refunds benefited core operating-profit growth by four percentage points. That makes the margin pressure worth a closer look: the quarter included a helpful refund and still produced a lower core margin.

There is a distinction between the two earnings measures. GAAP EPS was $2.23, up 17%; core EPS removes specified items and grew much more slowly. Mixing the GAAP growth rate with the core guidance would make the outlook look better than the like-for-like comparison supports.

Shares were up 2.16% at $126.40 at 7:52 a.m. ET. Investors were initially looking past the guidance cut, but the operating question remains straightforward: can PepsiCo rebuild unit demand while funding investment and absorbing higher costs? The segment tables show where the pressure is concentrated.

Read PepsiCo’s segment results and revised guidance →

FINANCING · WOLF

Wolfspeed gets a $1.5B offer—with strings attached.

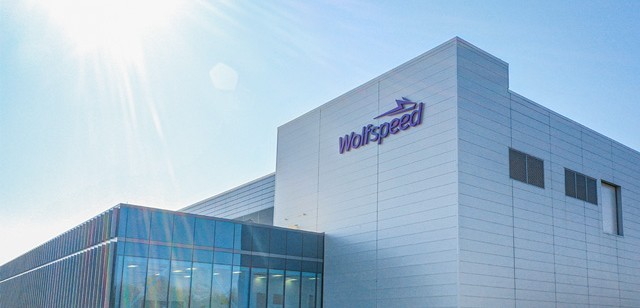
Wolfspeed manufacturing facility in New York

Wolfspeed facility · company photograph

Wolfspeed, the maker of silicon carbide materials and power chips, received a conditional commitment for up to $1.5 billion of government financing after Wednesday’s close. The proposed loan runs for 30 years. Shares were up 12.69% at $35.35 at 7:53 a.m. ET.

The first proposed tranche is $600 million, intended to refinance secured notes due in 2030 and pay related expenses. A further $900 million would support the manufacturing program, with draws contemplated over a 36-month commitment period.

That distinction matters. The full $1.5 billion would not land as fresh cash for expansion on day one. A substantial first piece would replace existing debt. Extending the financing horizon could give the company more time to develop production capacity before a nearer-term maturity comes due.

The government wants domestic capacity in silicon carbide and gallium nitride, technologies used in power electronics and defense applications. Wolfspeed plans to develop manufacturing, communications-related technology and radiation-hardening capabilities. This is an industrial-policy commitment tied to specific work.

Shareholders would help fund the arrangement. The contemplated terms include government warrants for up to 7.5% of fully diluted equity, issued as loan tranches are funded. Wolfspeed must also meet a qualifying-contribution requirement of at least $750 million. Eligible sources extend beyond newly raised cash and include specified equity and debt-conversion arrangements.

Final agreements, due diligence, government approvals and other conditions remain outstanding. The commitment is therefore a route to financing, rather than money already received. Those conditions belong in the headline discussion, not buried after the stock move.

Thirty years is meaningful breathing room for a capital-intensive manufacturer. It does not remove the need to produce chips efficiently or win enough business to support the facilities. The useful next milestone is signed financing with settled terms, followed by the first funded tranche—not another announcement of the same headline amount.

Read the financing announcement →

7 Stocks Built to Hold Forever. See the Full List.

Chasing the next hot stock can be exhausting, and it rarely builds wealth the way investors expect. The strongest long-term portfolios are often anchored by durable, blue-chip businesses designed to withstand recessions, inflation and shifting market leadership.

MarketBeat’s free 7 Stocks to Buy and Hold Forever report identifies companies across technology, retail, consumer staples, healthcare, networking, sporting goods and utilities. Each offers its own mix of stability, income, growth and staying power.

These are not speculative names built around the latest headline. They are established businesses selected for investors who would rather own quality companies for years than constantly chase the market.

Get your complimentary copy and see all seven names today.

THE SCOREBOARD

Where big tech finished

October 7 regular-session close · USD · Daily change.
Mag 7 plus AMD, Broadcom and Micron; our editorial watchlist.

Stock Close Change
Apple $336.67 +0.91%
Microsoft $529.76 +0.09%
Nvidia $237.47 −0.74%
Amazon $259.92 +1.42%
Alphabet $350.50 +0.81%
Meta $721.31 −2.38%
Tesla $377.81 −0.75%
AMD $645.86 −0.55%
Broadcom $376.51 +0.19%
Micron $1,088.00 +4.06%

AI INFRASTRUCTURE · APLD

Applied Digital’s revenue jumps. So does the financing bill.

Applied Digital data center campus under construction

Applied Digital campus · company photograph

Applied Digital reported $341.9 million of fiscal first-quarter revenue, up 322%, after Wednesday’s close. Its adjusted loss narrowed to one cent a share. Shares were up 0.97% at $24.04 at 7:53 a.m. ET after falling 6.04% in the regular session.

The mix deserves attention. Its high-performance-computing business included $183.5 million of tenant fit-out services and $65.8 million of base rent. Preparing space for customers generates real revenue, but it is different from the recurring rent investors expect a completed data center to collect.

The GAAP loss attributable to common shareholders from continuing operations was $221 million. Interest expense reached $77.4 million, and the company ended August with $6.4 billion of debt against $3.7 billion of cash, equivalents and restricted cash. Restricted cash is not all freely available to spend.

Polaris Forge 1 now has 250 megawatts operating, and management expects its North Dakota campuses to reach 300 megawatts by year-end. More operating capacity can bring more rent; the financing costs arrive along the way. The revenue split gives readers a better handle on that transition than the growth percentage alone.

The company’s adjusted measures also exclude its majority-owned ChronoScale business. The reconciliation is essential when comparing the near-break-even adjusted result with the much larger GAAP loss.

See the rent, fit-out revenue and earnings reconciliation →

AI DEALS · META

Manus raises $500M-plus after separating from Meta.

Manus has new funding and its independence back. Parent company Butterfly Effect said Thursday it raised more than $500 million after unwinding Meta’s acquisition, which had been valued at more than $2 billion, Reuters reported.

Boyu Capital and IDG Capital co-led the round. Existing investors including Tencent, Sequoia China and ZhenFund also participated. Manus develops AI agents that carry out tasks such as research and automation with limited human direction.

Beijing ordered the acquisition unwound in April, and Manus said in August that it would resume independent operations. Today’s round gives the newly standalone business substantial funding after losing the financial backing that ownership by Meta would have provided.

For Meta, this illustrates a practical constraint on buying AI capabilities across borders: paying for a business does not guarantee that regulators will let it stay inside the group. For Manus, the capital provides another way to fund development without remaining part of Meta.

The new round does not, by itself, establish a valuation or prove the business is profitable. It does establish that outside investors were willing to finance the standalone company after the acquisition fell apart.

See who backed Manus’s new funding round →

MACRO

Waller leaves room to skip a meeting.

Fed Governor Christopher Waller said this morning that additional rate hikes would likely be needed if the economy develops as expected. But they need not happen at consecutive meetings. That leaves room for an October pause without abandoning further tightening.

For stocks, the distinction is the timing of higher borrowing costs—not a promise of rate cuts. Yesterday’s minutes pointed toward another increase; today’s comments make clear that the schedule remains flexible.

Read Waller’s explanation of the rate path →

PREDICTION MARKETS

Traders still favor an October hold.

Polymarket’s October Fed contracts implied roughly 84.5% for no change and 14.5% for a quarter-point hike in the 7:48 a.m. ET update. Those are market-implied probabilities, not a Fed forecast; other outcomes account for the small remainder.

A hold this month and a later increase can both fit Waller’s message. The October contract alone says little about how high rates could finish the year.

Check the live October contracts and resolution rules →

UPGRADES & DOWNGRADES

Fresh calls on servers, restaurants and power.

SMCI: Citi raises its target to $45 from $39; a target change, not a rating upgrade.

CAVA: Melius upgrades to Buy from Hold, with a $95 target.

GNRC: KeyBanc upgrades to Overweight, targeting $280. Piper Sandler separately initiates at Overweight / $303.

HUT: Roth resumes at Buy / $108. This call was reported October 7; it is a prior-session update.

Analyst targets are opinions, not promised returns. Calls surfaced through Fiscal.ai.

CRYPTO OVERVIEW

Bitcoin near $82,500; Coinbase lost ground Wednesday.

Bitcoin: $82,526. Ether: $2,538. Coinbase spot-price snapshots retrieved at 7:53 a.m. ET; rounded to the nearest dollar.

Coinbase shares closed Wednesday at $178.45, down 3.92%. That is the completed stock session, separate from this morning’s round-the-clock crypto prices. The business depends on trading activity as well as asset prices, so a change in bitcoin does not translate directly into the same change in Coinbase revenue.

Follow bitcoin’s live price on Coinbase →

Forwarded this email? Get Cash & Chaos in your inbox.

Premarket stock snapshots: Yahoo Finance, October 8, 7:52–7:53 a.m. ET; changes versus October 7 regular closes. For information, not personalized investment advice.