|
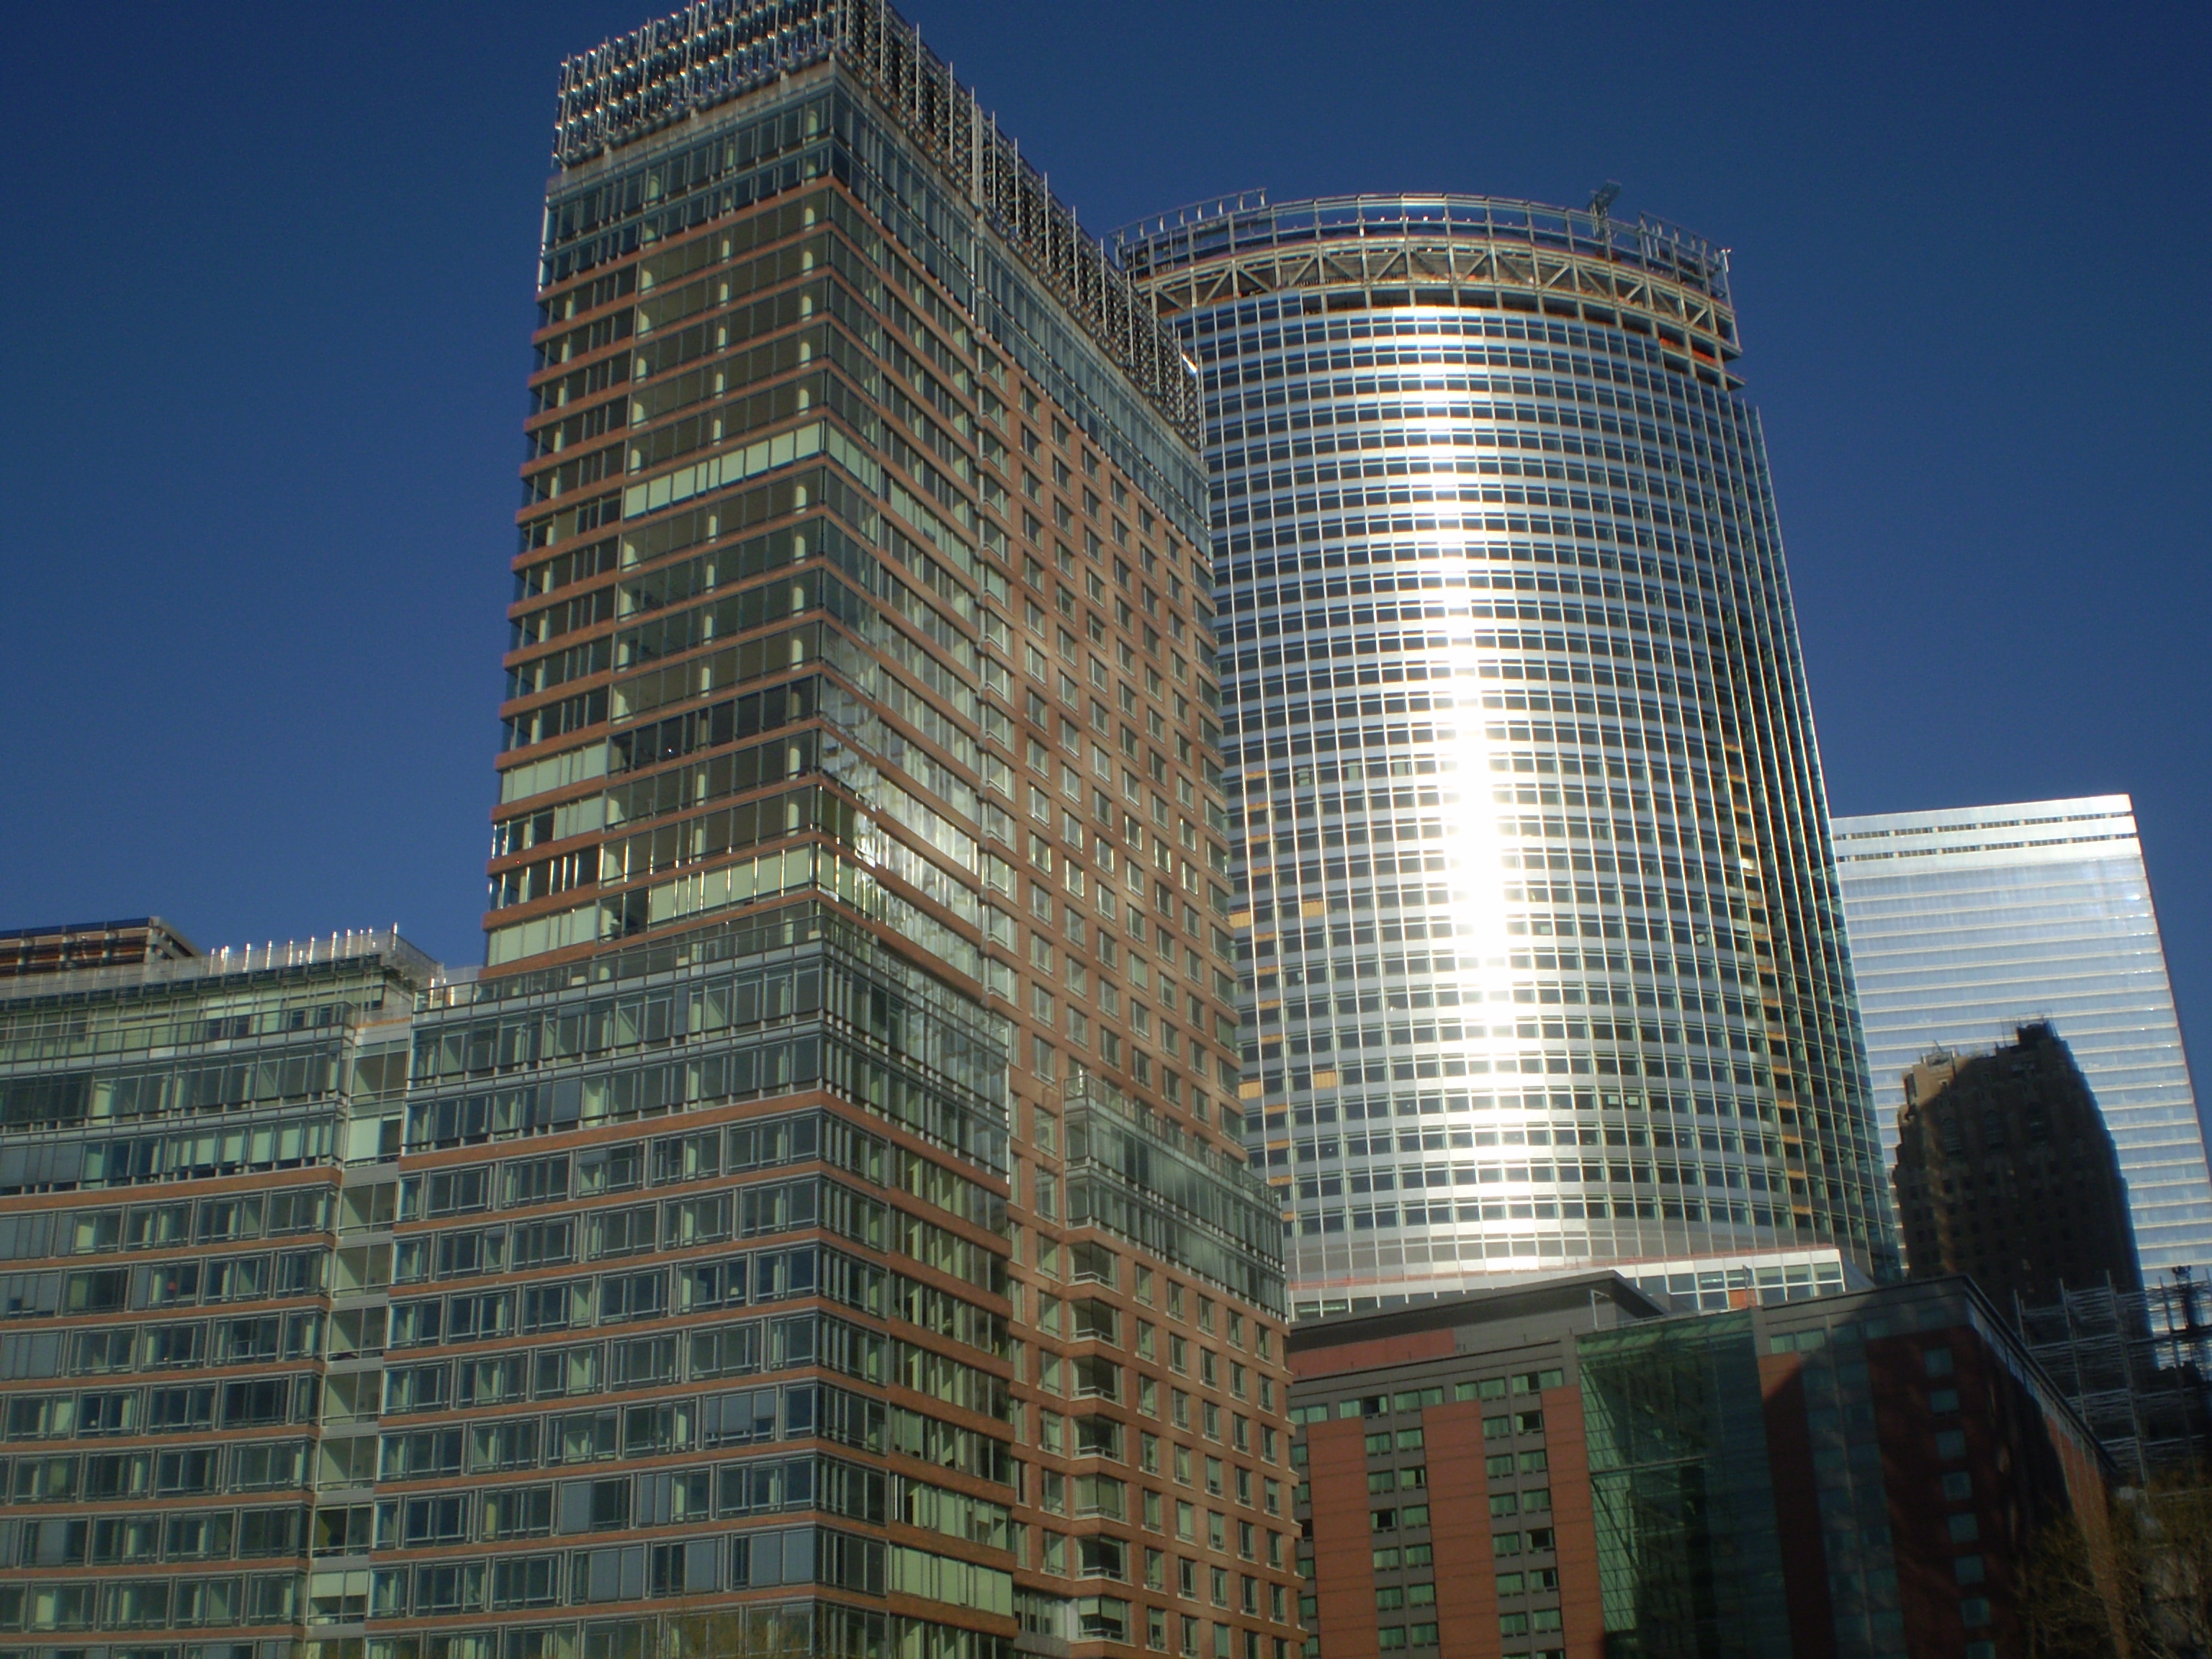
Goldman Sachs’ New York headquarters, 2009 archive. Photo: Z4dude / Wikimedia Commons · public domain.
JPMorgan, Goldman Sachs, Wells Fargo and Citi report Tuesday before the opening bell. Bank of America and Morgan Stanley follow Wednesday. The table gives us a consistent starting point: Zacks analyst consensus for adjusted EPS and revenue, rather than mixing figures from different providers.
Q3 2026 consensus, USD; estimates, not results. Latest available via Fiscal.ai, retrieved October 12. Individual estimates last changed October 2–8. Data provided by Zacks Investment Research, Inc., www.zacksdata.com
JPMorgan: start with net interest income—the gap between interest earned and interest paid—then look at deposit costs and provisions for credit losses. Higher lending rates help only if the bank keeps enough of the extra income after paying savers and accounting for loans that may go bad.
Goldman Sachs: the more revealing lines are advisory fees, underwriting and trading. A busy deal calendar can create fee income, while market volatility can encourage clients to trade. Neither guarantees a strong quarter: completed transactions pay the bills, and compensation absorbs part of the revenue.
Wells Fargo and Citi: compare revenue growth with expenses and credit provisions. A bank can beat EPS because costs fell, because its underlying business improved, or because it set aside less for future losses. Those are very different reasons to raise expectations for the next quarter.
Wednesday’s follow-through: Bank of America offers another read on lending income and deposit pricing. Morgan Stanley adds a wealth-management check: client assets and incoming money can support recurring fees, giving investors a different earnings mix from dealmaking alone.
The timing is worth saving. JPMorgan’s release is expected around 7 a.m. ET, Goldman’s at 7:30, and Citi’s at 8. Tuesday’s calls run JPMorgan at 8:30, Goldman at 9:30, Wells Fargo at 10 and Citi at 11. Wednesday’s releases are expected at 6:45 for Bank of America and 7:30 for Morgan Stanley.
A small EPS beat will make the first headline. The more durable signal is whether management’s outlook supports another quarter of growth without a matching increase in funding costs, bad debts or operating expenses. Keep the estimates beside the results, then read the bridge between revenue and profit.
|