FRIDAY, OCTOBER 9, 2026  /  10-MINUTE READ

CASH & CHAOS

MARKETS, MONEY AND THE MADNESS IN BETWEEN.

In partnership with

Good morning. Apple reportedly wants fewer iPhone parts. Delta has plenty of passengers, but fuel is eating into the benefit. And SpaceX has signed a spectrum deal that gives America’s wireless giants something else to worry about.

There is better news for one corner of the AI trade: Lumentum says its optical-component capacity is booked into 2029. We’ll also untangle OpenAI’s $50 billion and $70 billion revenue figures, because those numbers have been doing a lot of damage without much explanation.

BEFORE THE BELL

+0.34% S&P 500
7,843.00
+0.73% Nasdaq 100
31,195.75
+0.01% Dow
51,499

December futures · October 9, 6:56 a.m. ET · delayed Yahoo Finance quotes; change versus prior close.

THE BIG STORY · AAPL

Apple reportedly cuts iPhone orders as prices bite.

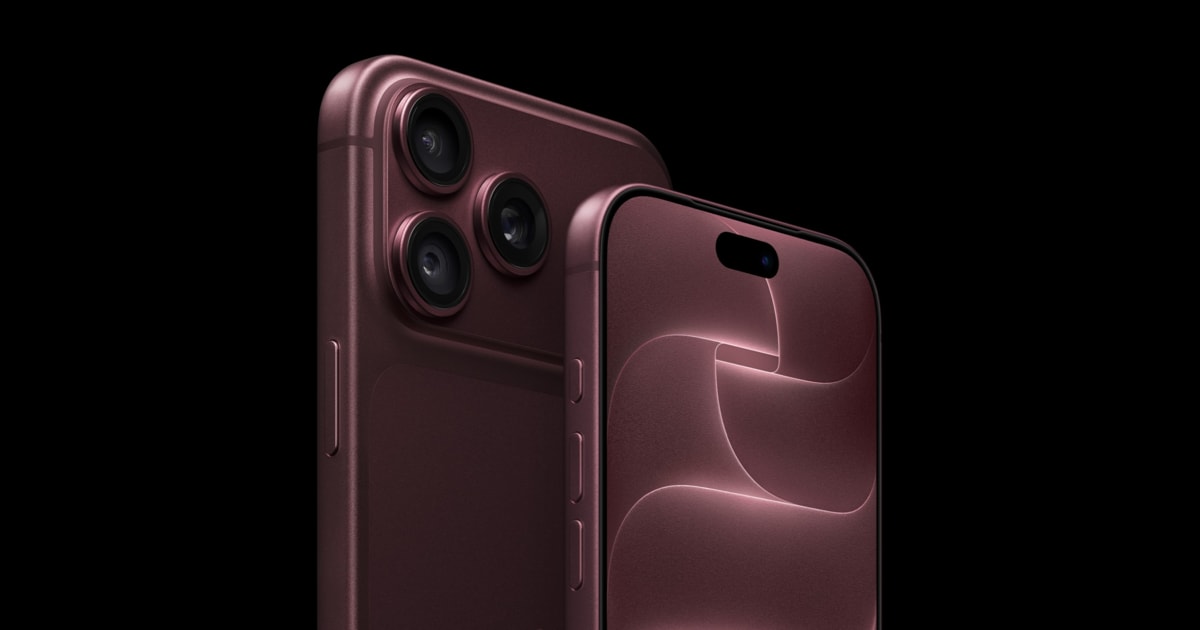
Apple iPhone 18 Pro models

Product image: Apple. Stock snapshot: October 9, 7:06 a.m. ET.

Apple traded at $334.36, down 1.78% premarket. Nikkei reports that some suppliers have been told to cut October component orders for the iPhone 18 Pro and Pro Max by at least 15% from the original plan.

The report points to softer demand and rising memory costs. Apple had not responded to Reuters, which could not independently verify it. These are reported component-order changes, not a disclosed 15% drop in iPhone sales.

Apple’s new Pro models start at $1,199 and $1,299, each $100 above its predecessor. That makes the financial trade-off fairly plain: passing higher parts costs to buyers can protect profit per phone, but it can also persuade someone to keep the phone already in their pocket.

The awkward part is that AI spending can help one technology company while squeezing another. Memory sold into a data center is revenue for a chip supplier. More expensive memory inside a handset is a cost Apple must absorb or pass along.

For shareholders, the next useful distinction is between a weaker launch and a weaker full holiday season. An early supply adjustment does not settle that question. The report also flags changes to Apple’s launch schedule as a possible influence on component demand.

Cutting orders promptly could prevent excess inventory and later discounting. But it would also leave suppliers with less production than they had budgeted for. That is why a supplier report can move stocks before it appears in a company’s quarterly accounts.

Our read: watch iPhone revenue, product mix and gross margin together. A higher average selling price can cushion fewer units; it cannot tell us whether customers are still upgrading at the pace Apple expected.

Read the supplier report and launch-timing details →

EARNINGS · DAL

Delta fills seats. Fuel takes a bigger cut.

Delta Airbus A350 in flight

Archival aircraft photo: Delta News Hub. Stock snapshot: October 9, 7:06 a.m. ET.

Delta fell 4.49% to $78.45 premarket after reporting $17.6 billion in adjusted revenue, up 16%, and adjusted earnings of $1.72 a share. A year ago, that earnings number was $1.71.

Passengers are spending more. Very little of that extra spending reached earnings per share. Adjusted fuel expense rose 62% to $4.1 billion, and fuel cost about $500 million more than Delta had assumed in its July outlook.

The revenue mix is encouraging. Premium revenue increased 18% on 6% more seats. Main-cabin unit revenue rose 17% while seat capacity declined slightly. Delta is getting more money from the space on its planes, rather than relying solely on adding flights.

That matters because extra flying brings extra fuel, crew and maintenance costs. Selling an existing seat at a better fare is generally more attractive than chasing volume at any price. This quarter, though, the fuel bill absorbed much of the improvement.

The holiday outlook makes that tension clearer. Delta expects fourth-quarter adjusted revenue to rise about 20%, but forecasts an operating margin of 7%–9% and adjusted EPS of $1.15–$1.65. Its fuel assumption is $4.25 a gallon, including the expected benefit from its refinery.

For the full year, management projects adjusted EPS of $5.10–$5.60 and roughly $2.5 billion in free cash flow. Cash generation gives the company room to reduce debt; it also provides a check on earnings that can look healthier before aircraft spending and other cash demands.

The earnings call starts at 10 a.m. ET. The useful follow-up is how much of the holiday pricing strength is already booked, and how quickly higher fuel costs can be recovered in fares. Today’s release shows demand holding up. The harder job is keeping enough of the money.

See Delta’s holiday outlook and revenue breakdown →

TELECOM · T / VZ / TMUS

SpaceX buys spectrum. Phone stocks get the message.

Starlink residential dish under a night sky

Illustrative residential hardware, not the proposed mobile service. Photo: SpaceX. Stock snapshots: October 9, 7:04–7:06 a.m. ET.

AT&T was down 6.92%, Verizon 6.67% and T-Mobile 7.65% premarket. SpaceX has signed an agreement to buy Grain Management’s nationwide 800 MHz spectrum portfolio, adding another piece to its wireless ambitions.

Grain announced the deal after Thursday’s close. The price was not disclosed, and the transaction still needs FCC approval and other closing conditions. A signed spectrum agreement does not mean a new nationwide mobile service is ready to switch on.

But the frequency matters. Lower-frequency spectrum can cover longer distances and penetrate buildings better than higher-frequency bands. It can complement bands used for capacity, making it a valuable ingredient in a broader communications network.

For the established carriers, the risk extends beyond losing a few customers in places with poor reception. Another credible provider could force more generous plans, cheaper bundles or larger spending commitments to keep customers. Even without a mass exodus, that can reduce returns on a very expensive network.

Consider the economics from a household’s side. Reliable coverage is part of what makes people tolerate a recurring phone bill. If another service can offer useful coverage at a lower incremental price, the incumbent has less room to charge a premium. The quality and price of the actual service will determine how far that argument goes.

SpaceX still has to turn spectrum rights into dependable capacity. Satellites, ground infrastructure, compatible devices and regulatory permissions all matter. Better coverage also does not automatically mean enough bandwidth to replace every customer’s existing connection.

For now, investors can put a signed asset purchase against those longer-term possibilities. The next concrete milestones are regulatory filings, a clearer service plan and disclosed economics. Thursday’s closing prices predate the announcement; the declines above are this morning’s separate market reaction.

Read the spectrum agreement and closing conditions →

The 10 Best AI Stocks to Own in 2026

AI is moving from experiment… to essential.

Every major industry is integrating it.
Every major company is investing in it.

By late 2025, AI was already an $800B market — growing at a pace that could push it well beyond $1 trillion in the years ahead.

Cloud infrastructure is scaling fast.
AI-enabled devices are multiplying.
Automation is becoming standard.

But here’s the real question…

When trillions flow into this transformation — which stocks stand to benefit most?

Our new report reveals 10 AI stocks positioned across the backbone of this shift — from the companies powering the infrastructure… to those embedding intelligence into everyday systems.

If you want exposure to one of the defining growth trends of this decade, start here.

MAG 7 + THREE

Where big tech finished

October 8 regular close · USD · Daily change. Mag 7 plus AMD, Broadcom and Micron; our editorial watchlist.

StockCloseChange
Apple$340.42+1.11%
Microsoft$522.61−1.35%
Nvidia$230.48−2.94%
Amazon$254.06−2.25%
Alphabet$348.29−0.63%
Meta$720.89−0.06%
Tesla$375.00−0.74%
AMD$620.68−3.90%
Broadcom$360.14−4.35%
Micron$1,035.84−4.79%

AI BUSINESS

OpenAI’s $20 billion gap needs an explanation.

Greg Brockman and Sam Altman at TechCrunch Disrupt in 2019

Archival photo, 2019: Steve Jennings / TechCrunch · CC BY 2.0.

OpenAI’s annualized revenue was roughly $50 billion at September’s end, according to Bloomberg. Overnight, the outlet reported that the company expects to reach or exceed $70 billion by year-end, helped by enterprise demand.

OPENAI REVENUE RUN RATE
Annualized revenue pace · USD billions
End of September 2026 · Reported: ~$50B
  
End of 2026 · Forecast: $70B+
  
Run rates are not full-year revenue. The forecast has not been achieved. Source: Bloomberg, October 8.

Those are different dates, and annualized revenue is a recent sales pace extrapolated over a year. It is not revenue already collected during the year. Earlier $70 billion estimates also used different treatment of sales through cloud partners, according to reporting on the accounting discrepancy.

So this is not a disclosed $20 billion quarterly earnings miss. It does leave investors needing consistent definitions before comparing AI companies or deciding how much infrastructure their sales can support. OpenAI declined to comment on Bloomberg’s report.

The financing backdrop makes that more than an accounting footnote. Broadcom has reportedly held early talks about roughly $30 billion in debt financing for infrastructure involving its custom chips and OpenAI. Talks are not committed funding.

Our read: a faster sales pace helps justify expansion, but annualized revenue cannot be spent twice. Cloud providers, chip suppliers and financiers ultimately need customers to generate cash sufficient to pay their bills. Investors need to know who earns the revenue, who carries the assets and who owes the debt.

Broadcom fell 4.35% and Nvidia 2.94% Thursday. That shows how a debate about a private company’s numbers can reach public portfolios through the businesses supplying it.

Read the September figure and year-end outlook →

AI HARDWARE · LITE

Lumentum has orders stretching into 2029.

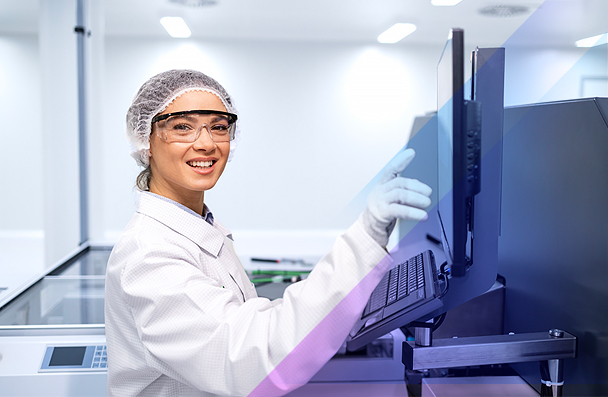
Technician working with equipment in a Lumentum cleanroom

Company cleanroom photo: Lumentum.

Lumentum rose 4.64% to $1,097.30 premarket. Its CEO told Bloomberg that optical-component capacity is booked through early 2029, giving investors a concrete demand signal after Thursday’s selloff.

These components help move data around AI systems. Buying more processors does not solve much if the machines cannot communicate quickly enough. That makes connectivity suppliers important beneficiaries of data-center construction, even when the best-known chipmakers take most of the attention.

The company described substantial unmet demand for particular products: as much as 70% next year in some cases, and 30% through 2028 for others. Those are product-specific claims, not a measure of the entire optical market.

For Lumentum, a full production schedule offers visibility and could strengthen pricing. It also puts a ceiling on near-term sales unless the company can increase usable output. Customers wanting more parts does not immediately create more parts.

The financial test is how quickly added capacity becomes qualified, shippable product, and what it costs to get there. New equipment and facilities require cash before they earn a return. Booked capacity is encouraging; delivered components and collected revenue are what eventually show up in the accounts.

Watch the CEO explain the capacity shortage →

MACRO

The consumer gets a check-in at 10.

The University of Michigan’s preliminary October sentiment report is due at 10 a.m. ET. September’s sentiment index was 48.1, with one-year inflation expectations at 4.6%. Today’s figures are still ahead.

For retailers and consumer stocks, the useful combination is how households feel about both their finances and future prices. Improving confidence alongside cooling inflation expectations would be more encouraging than either reading alone.

Check the release and inflation-expectations tables →

PREDICTION MARKETS

An October hold remains the favorite.

Polymarket’s no-change contract priced an October Fed hold at 84.5%; its quarter-point-hike contract was at 15.5% in the 7:04 a.m. ET snapshot. These are separately traded market prices, not a Fed forecast.

The contracts resolve using the change in the upper bound of the target rate after the October 27–28 meeting.

Check the current prices and resolution rules →

UPGRADES & DOWNGRADES

Goldman turns more bullish on Palantir.

PLTR: Goldman Sachs upgraded the stock to Buy from Neutral on October 8, with a $230 12-month target. The firm sees more opportunity in sovereign AI and software tailored to individual customers.

The call is about expanding the addressable market and sustaining delivery to customers. It is an analyst’s assessment, not new company guidance. This is yesterday’s rating change, carried forward for context.

Read the reasoning behind Goldman’s upgrade →

CRYPTO OVERVIEW

Bitcoin near $82,500. Coinbase had a rough Thursday.

Bitcoin: $82,462. Ether: $2,490. Coinbase spot snapshots retrieved at 7:06 a.m. ET, rounded to the nearest dollar.

Coinbase shares closed Thursday at $172, down 3.61%. Exchange revenue depends on trading activity and fees as well as asset prices. A volatile market can produce transactions even when coin prices fall, so the stock and bitcoin need not move together.

Follow bitcoin’s live price on Coinbase →

Forwarded this email? Get Cash & Chaos in your inbox.

Premarket stocks: Yahoo Finance, October 9, 7:04–7:06 a.m. ET; changes versus October 8 regular closes. For information, not personalized investment advice.