|
THE STOCK BOARD
Where big tech finished
Monday, September 28 close · Prices in USD · Daily change
Mag 7 + AMD, Broadcom and Micron. C&C’s editorial watchlist.
| Stock |
Close |
Monday |
| Apple |
$338.40 |
−0.78% |
| Microsoft |
$509.22 |
−1.35% |
| Nvidia |
$228.86 |
+1.68% |
| Amazon |
$246.15 |
−1.41% |
| Alphabet |
$342.75 |
−0.34% |
| Meta |
$715.62 |
−4.79% |
| Tesla |
$357.45 |
−3.94% |
| AMD |
$607.87 |
−3.61% |
| Broadcom |
$349.57 |
−0.92% |
| Micron |
$1,053.98 |
−2.61% |
Nvidia was the only gainer in this group. Its strength didn’t extend across the chip stocks, and the largest losses came from Meta and Tesla. Monday’s board is a good reason to look past the label “AI trade”: these companies have different customers, costs and announcements.
|
|
IN FOCUS · MDB
Meta hired MongoDB’s CEO. The stock lost 18%.

BrokenSegue ·
CC BY-SA 4.0. Palo Alto office, 2014 file photo.
Meta got a new executive. MongoDB shareholders got a rough Monday.
CJ Desai left MongoDB for a senior role at Meta, effective immediately. MongoDB brought back former CEO Dev Ittycheria on an interim basis while it searches for a permanent replacement. The company’s announcement.
|
$334.68
Monday close
|
−18.46%
Monday change
|
$300.00
Session low
|
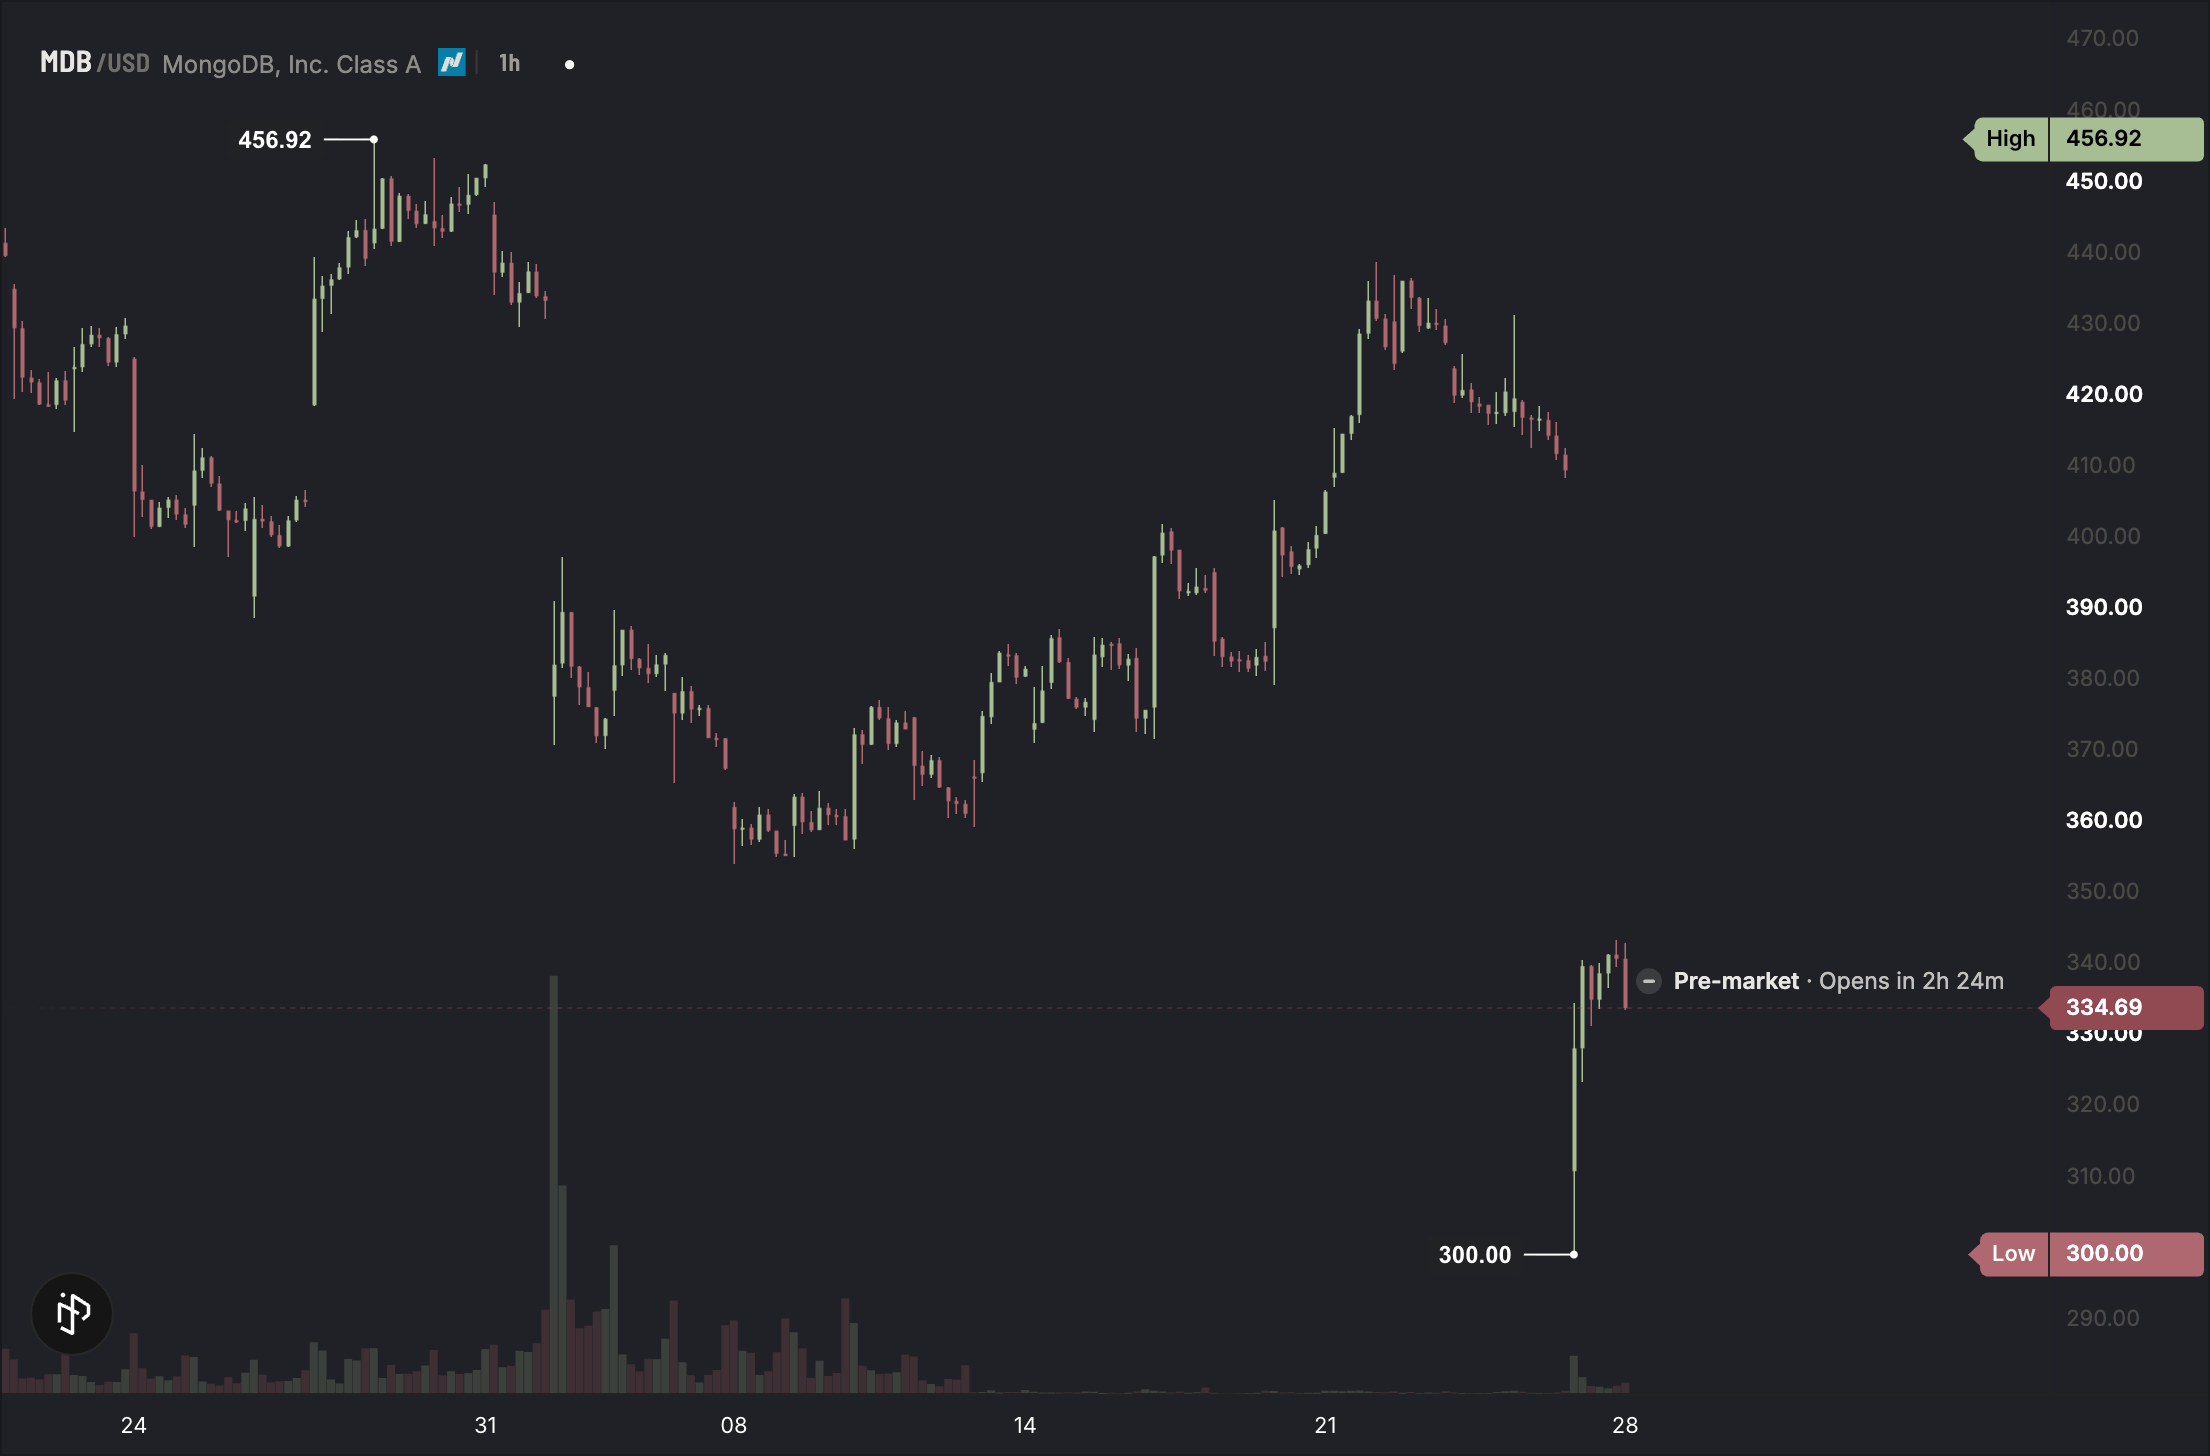
Source: OpenMarket · view the chart. Hourly candles. Supplied September 29; the $334.69 premarket marker is separate from Monday’s $334.68 official close.
Shares closed at $334.68, down 18.46%, after trading as low as $300. The OpenMarket chart shows the sharp gap lower and the recovery from the session’s low. Even after that rebound, the shares finished $75.76 below Friday’s close.
The forecast hasn’t changed. MongoDB reaffirmed its third-quarter and full-year fiscal 2027 guidance. That makes the selloff particularly striking: investors marked down the shares despite management leaving its financial outlook intact.
Leadership uncertainty can matter well before it shows up in reported revenue. Investors now need to hear who owns the strategy, whether senior staff and customers stay confident, and how the permanent CEO search will work.
Today’s 11 a.m. ET investor day puts management in front of shareholders almost immediately. The useful answers will concern execution and continuity, rather than another broad pitch about AI demand.
|
|
AI & BUSINESS · META
Meta wants a place in the back office
Today’s Muse for Small Business announcement gives Meta’s enterprise ambitions something tangible.
The company is adding connections to tools including QuickBooks, Shopify, Slack and Stripe, alongside Facebook and Instagram business accounts. The pitch is an agent that can work across the systems a business already uses, with the owner giving it a goal rather than managing every step. See Meta’s launch details.
For shareholders, the opportunity goes beyond generating marketing copy. If an assistant becomes part of daily operations, it could give Meta another recurring relationship with businesses. But access to an account is not the same as permission to run the company. Reliability, controls and the cost of serving users will matter as usage grows.
|
|
AI & POLICY · NVDA
The AI argument moves to Washington

Coolcaesar; edit by Jacek Halicki ·
CC BY-SA 4.0. File photo.
President Trump and House Speaker Mike Johnson are expected to meet leading AI executives today, with oversight and the pace of development under discussion. A meeting is on the calendar; an agreement is not yet a fact. What is planned.
Nvidia’s response to the safety debate includes the Open Agent Safety Platform announced yesterday. OpenShell controls what an agent can access and do at runtime. Sentry adds a separate protection layer intended to isolate suspicious activity.
That is a proposed way to make deployments safer, not proof that unpredictable AI behavior has been eliminated. More than 100 organizations participating in the initiative also doesn’t mean 100 paying customers are already running it in production. Nvidia’s description of the system.
The business issue is practical. Companies buying autonomous software need confidence that it won’t create an expensive problem while completing a routine task. Better controls could support adoption; more demanding approval requirements could slow launches or raise costs.
For the listed suppliers, today’s useful developments would be specific requirements, implementation dates or procurement commitments. Broad statements about leadership tell us much less about next quarter’s revenue.
|
|
AROUND THE MARKET
A few stocks outside the AI conversation
Boeing
The FAA is delaying MAX 10 certification while a newly disclosed software issue is addressed. Boeing fell 6.91% Monday. The consequence to follow is delivery timing: a backlog generates cash only as aircraft can be completed and handed over. This is a MAX 10 certification setback, not a newly announced grounding of every MAX. Read the reporting.
Ford and GM
The final fuel-economy rollback gives automakers more flexibility over their vehicle mix. DOT projects a 34.9 mpg fleetwide average in 2031 under the new standards. That is a regulatory fleet calculation, not a requirement that every vehicle achieve that mileage. Lower compliance spending could help manufacturers; customers still have to live with the fuel bill. The final announcement.
Novo and Lilly
Novo is paying $300 million upfront for rights outside greater China to Hengrui’s early-stage, potentially weekly oral obesity treatment. Meanwhile, Lilly released a favorable indirect comparison of Foundayo against a higher-dose oral semaglutide regimen. These developments belong at different points on the research timeline. Novo is acquiring a candidate ready for Phase 1; Lilly’s comparison uses existing studies rather than a new randomized head-to-head trial. Neither headline establishes future market share. Novo’s agreement · Lilly’s study details.
|
|
EARNINGS AHEAD · MU / NKE
Micron tomorrow, Nike Thursday

Brandon Carson; crop by Another Believer ·
CC BY 2.0. Source crop.
WEDNESDAY · MICRON
June’s outlook called for quarterly revenue of $50 billion, plus or minus $1 billion, and gross margin of approximately 86%. Those are management’s previous forecasts, not results already reported. Last quarter’s adjusted free cash flow was $18.3 billion after $7.1 billion of net capital expenditure.
Tomorrow’s update should show whether demand and pricing delivered against that outlook—and how much additional investment is needed to keep supplying customers. High margins are valuable, but the duration of those margins helps determine what investors should pay for them. Micron’s previous results and guidance.
THURSDAY · NIKE
Its previous quarter produced $11 billion of revenue, down 1%, with direct sales down 7%. The reported 49.2% gross margin included roughly nine percentage points from expected tariff recoveries.
Thursday’s release needs a reading that separates those benefits from the underlying business. Wholesale growth, direct-channel demand and discounting will give a better picture of the recovery than an earnings figure helped by tariff accounting. Nike’s prior-quarter breakdown.
|
|
STREET CALLS
Upgrades, downgrades and target changes
Three relevant calls from Monday, rather than fresh Tuesday actions:
|
Micron: Baird raised its target from $1,280 to $1,520, maintaining Outperform. A target increase, not a rating upgrade.
The call.
|
|
Nike: Deutsche Bank lowered its target from $45 to $37, maintaining Hold. A target cut, not a downgrade.
The call.
|
|
Royal Caribbean: Deutsche Bank upgraded Hold to Buy, with a $299 target. This one changed the recommendation.
The call.
|
For Micron and Nike, the upcoming results give us a quick opportunity to compare those views with updated company numbers.
|
|
PREDICTION MARKETS
Prediction markets: another hike is the favored outcome
|
70%
Quarter-point hike
|
30%
No change
|
Kalshi’s October Fed market displayed approximately 70% for a quarter-point hike and 30% for no change in this morning’s check.
These are market-implied probabilities, not a Fed forecast. Separate contracts, spreads and rounding can produce totals above 100%; the page also displayed a small probability of a larger hike.
For stock investors, the connection is financing costs and the valuation of future earnings. The odds can shift as this week’s data arrives. Follow the October contract.
Observed September 29, approximately 6:28 a.m. ET.
|
|
MACRO IN A MINUTE
At 10 a.m., two more views of the consumer
August job openings and September consumer confidence are scheduled for 10 a.m. ET today. Openings describe employers’ demand for workers; confidence describes households’ perceptions. Neither is a substitute for actual spending.
For retailers, lenders and travel stocks, the useful combination is whether employment opportunities are holding up while consumers remain willing to make larger purchases. CarMax supplies company-level evidence; the broader releases can show whether that experience travels beyond one business. BLS schedule · Consumer confidence.
|
|
CRYPTO STOCKS
Crypto stocks, briefly
Coinbase fell 1.70% Monday, while Strategy lost 0.93%. These are regular-session stock returns. They offer different exposures: exchange activity and fees for Coinbase, versus bitcoin holdings and financing decisions for Strategy. Neither return should be presented as bitcoin’s overnight move.
|
|
Forwarded this email? Get Cash & Chaos in your inbox.
|
|